Latest posts
-
Insurance Cancellation and Nonrenewal Basics
Insurance cancellation and nonrenewal are not the same thing. Knowing the difference helps you understand when protection ends and how quickly you may need replacement coverage. Cancellation Cancellation generally ends a policy before its scheduled expiration date. The notice should identify the effective date and, where required, the reason and available rights under local rules.…
-
Insurance for Home-Based Businesses

Operating a business from home can create risks that a standard homeowners or renters policy may limit or exclude. A home office, inventory, client visits, and business equipment should be reviewed separately from personal property. Identify the business exposures Computers, tools, stock, and specialist equipment. Customers, couriers, or contractors visiting the property. Professional advice or…
-
How to Compare Insurance Quotes Fairly
Comparing insurance quotes fairly means comparing the protection behind the price. Two quotes can look similar while using different limits, deductibles, exclusions, or assumptions about your risk. Start with an apples-to-apples checklist Write down the insured property, drivers, business activities, travel dates, health benefits, or other details relevant to the policy. Give each insurer the…
-
Insurance Glossary: Essential Terms to Know
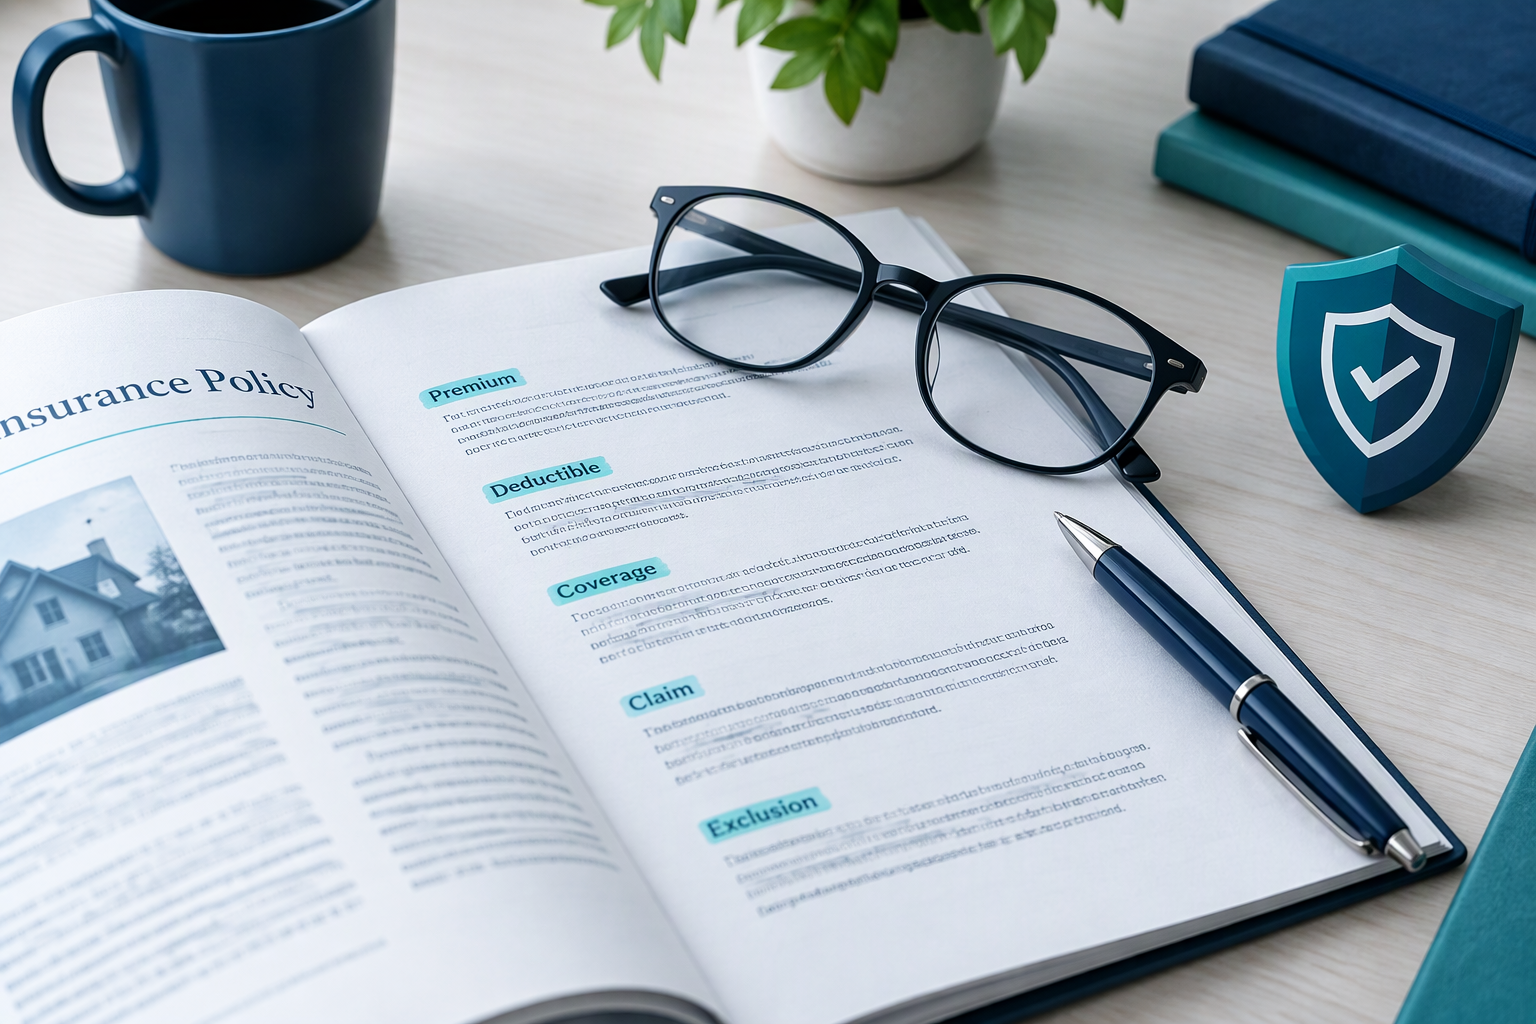
Insurance language can feel complicated, especially when a policy uses similar words for very different ideas. This practical glossary explains the terms that most often affect your premium, claim, and coverage decision. Premium, deductible, and limit Your premium is what you pay for the policy. A deductible is the amount you generally pay toward a…
-
Health Insurance Provider Networks Explained
A health insurance provider network is the group of doctors, hospitals, pharmacies, laboratories, and other professionals connected to a plan. Network status can affect both your choice of provider and the amount you pay. In-network and out-of-network care In-network providers have an arrangement with the plan. Out-of-network care may cost more, may require additional approval,…
-
Insurance for New Drivers
New drivers need more than a low premium. They need a policy that accurately reflects who drives, how the vehicle is used, and what happens after an accident. Coverage to understand Liability coverage addresses covered harm to other people or property. Collision may address damage from a crash, while comprehensive may address certain non-collision losses…
-
Insurance for Rental Property Owners

Rental property insurance should be built around the risks of owning a property occupied by tenants, not the risks of living in your own home. Coverage areas to review Ask about the building, landlord liability, loss of rental income, equipment, vandalism, water damage, and legal expenses where applicable. A tenant’s belongings are usually handled through…
-
How Insurance Policy Limits Work

A policy limit is the maximum amount an insurer may pay for a covered loss or category of loss, subject to the contract. Limits should be reviewed with deductibles, exclusions, and sublimits. Common limit structures A policy may use per-occurrence, per-person, annual aggregate, per-item, or sublimits for specific property or services. One policy can contain…
-
Insurance Record-Keeping System for Families

A family insurance record system makes it easier to find documents after a move, claim, renewal, or emergency. The goal is simple: one secure place for the information you need. What to keep Declarations pages and policy wording. Premium receipts and renewal notices. Home and vehicle inventories. Beneficiary confirmations and emergency contacts. Claim numbers, estimates,…
-
Insurance for Freelancers and Independent Contractors

Freelancers and independent contractors can face professional, property, cyber, vehicle, and liability risks that personal insurance may not fully address. Map your actual work List the services you provide, advice you give, equipment you use, client data you handle, locations you visit, and subcontractors you hire. Coverage questions Ask about professional liability, general liability, business…
-
Insurance for High-Value Jewelry and Collectibles
Jewelry, watches, art, collectibles, and other valuable items may have special limits under a standard home or renters policy. A separate endorsement or specialist policy may be needed. Review the valuation method Ask whether the policy uses actual cash value, agreed value, or another method. Check theft limits, mysterious disappearance, accidental damage, deductibles, and appraisal…
-
Insurance Waiting Periods Explained
A waiting period is the time that must pass before certain benefits begin or become available. It can affect health, pet, travel, income, and other insurance products. Questions to ask When does the waiting period start? Which benefits or conditions does it affect? Are accidents treated differently? Does changing plans restart the period? What happens…
-
How to Read an Insurance Declarations Page

The declarations page is a short summary of the policy, but it is not the complete contract. Read it together with the definitions, exclusions, conditions, and endorsements. Check the key details Named insured and address. Policy start and end dates. Covered property, vehicles, or people. Limits, deductibles, and premium. Listed drivers, beneficiaries, and endorsements. Look…
-
Insurance and Preventive Maintenance
Insurance is designed for covered risks, not ordinary maintenance. Regular inspections and repairs can reduce preventable damage and help you document the condition of your property. Useful records to keep Save service invoices, roof and plumbing inspections, appliance details, photographs, safety checks, and repair receipts. Read your policy duties Some policies require reasonable care, prompt…
-
How Auto Insurance Coverage Types Differ
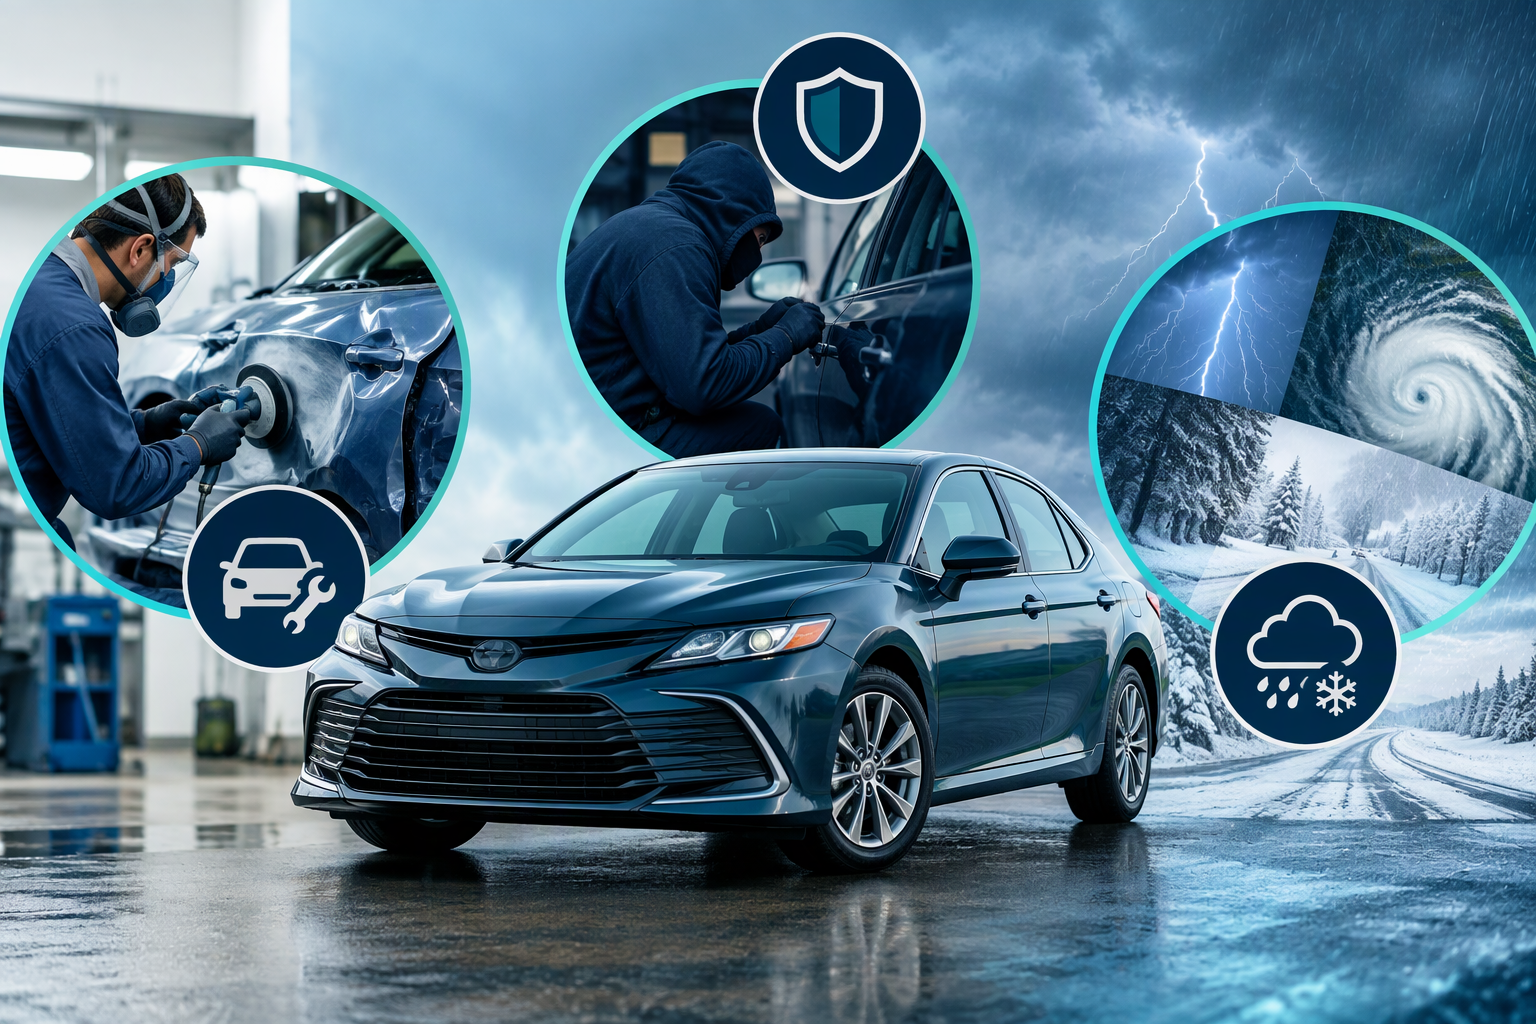
Auto insurance is usually a package of different protections rather than one single benefit. Understanding each part helps drivers choose limits that match their situation. Common coverage types Liability may address covered harm to others. Collision may address damage from a crash. Comprehensive may address selected non-collision losses such as theft, weather, or falling objects.…
-
Renters Insurance for Apartment Tenants

Renters insurance can help address covered losses involving personal belongings and may include personal liability or additional living expense benefits, depending on the policy. What tenants should check Contents limits and high-value item sublimits. Deductible and claim valuation method. Personal liability limit. Temporary relocation or additional living expense rules. Roommate, home business, and pet-related conditions.…
-
Flood Insurance Basics for Property Owners
Flood insurance should be reviewed separately from other water-related risks because policies may define flood, surface water, storm surge, sewer backup, and water entering through another route differently. Ask what the policy means by flood Do not assume that every type of water damage has the same coverage. Check the definition, waiting period, deductible, exclusions,…
-
Business Interruption Insurance Explained
Business interruption insurance may help address certain lost income or continuing expenses after a covered event interrupts operations. The policy wording controls the trigger and calculation. Review the important terms Check the covered event, waiting period, period of restoration, revenue definition, payroll treatment, extra expense coverage, sublimits, and exclusions. Prepare before a loss Keep financial…
-
Cyber Insurance for Small Businesses

Cyber insurance may help a business respond to selected costs from a covered data breach, ransomware event, system outage, or liability claim. It does not replace strong security controls. What insurers may ask Applications can ask about multifactor authentication, backups, access control, staff training, monitoring, and incident response. Keep answers accurate and current. Coverage areas…
-
Umbrella Insurance: When Extra Liability May Matter
Umbrella insurance may provide additional liability protection above certain underlying home, auto, or other policies. It is designed for serious covered claims that exceed primary limits. How it fits with primary coverage An umbrella policy may require minimum liability limits on the underlying policies. It generally does not replace them, and exclusions or retained amounts…
-
What Does Liability Insurance Cover?
Travel insurance can help address selected medical, cancellation, interruption, baggage, and emergency-assistance risks during an international trip. Coverage varies widely, so the policy should be reviewed before departure. Medical protection abroad Check emergency treatment limits, evacuation and repatriation, hospital admission procedures, pre-existing condition rules, and whether the destination is covered. Trip cancellation and interruption Read…
-
Pet Insurance: Questions to Ask Before Enrolling
Pet insurance can help manage selected veterinary costs, but plans differ widely. The most useful comparison looks beyond the monthly premium. Check eligibility and exclusions Ask how the plan treats pre-existing conditions, hereditary conditions, congenital conditions, preventive care, dental treatment, prescription medicines, specialist care, and emergency services. Understand reimbursement Confirm whether reimbursement is based on…
-
Home Insurance Inventory: A Simple Guide
A home inventory is a practical record of your belongings. It can help you estimate whether your contents limit is realistic and organize evidence after a covered loss. What to include Record furniture, electronics, appliances, clothing, tools, jewelry, collectibles, and high-value items. Note brand, model, serial number, purchase date, estimated value, and receipt location. Use…
-
What Is Coinsurance in Health Insurance?

Coinsurance is the percentage of an allowed covered health expense that you may pay after meeting a deductible. It is different from a copayment, which is usually a fixed amount for a service. How the sequence may work A plan may require the deductible first, then apply coinsurance until you reach an out-of-pocket maximum. The…
-
Travel Insurance Before an International Trip
Liability insurance generally helps address covered legal or financial responsibilities when an insured person or business is alleged to have caused injury, property damage, or another covered loss. Personal liability Home and renters policies may include personal liability for selected incidents involving the household or property. Limits, exclusions, and defense provisions vary. Business liability General…
-
Term Life Insurance vs Whole Life Insurance
Term life and whole life insurance are designed for different planning needs. The best comparison looks at the goal, length of protection, cost, flexibility, and contract guarantees. Term life insurance Term coverage protects the insured for a stated period. Families often consider it for income replacement, education funding, debt protection, or a mortgage during working…
-
How Deductibles Work in Insurance
An insurance deductible is the amount you generally pay toward a covered loss before the insurer contributes, subject to the policy terms. It is one of the most important figures when comparing the real cost of coverage. Higher versus lower deductibles A higher deductible may reduce the premium, while a lower deductible can make a…
-
How to Make an Insurance Claim Checklist
A clear claim checklist helps you organize information after a covered event. Safety comes first, followed by prompt notice, accurate records, and careful communication. 1. Make the area safe Call emergency services when necessary and take reasonable steps to prevent further damage. Do not make unsafe repairs or discard damaged items unless they create a…
-
What Is an Insurance Exclusion?
An insurance exclusion is a situation, cause of loss, person, property, or service that a policy does not cover. Exclusions are important because a policy can appear broad while still limiting specific risks. Common exclusions Policies may exclude intentional damage, normal wear and tear, certain natural disasters, undeclared business use, pre-existing conditions, or losses that…
-
Insurance Beneficiaries: What to Review
A beneficiary is a person, trust, or organization named to receive proceeds from certain insurance policies. Keeping the designation current can help prevent delays and conflicts. Review major life events Marriage, divorce, births, deaths, adoption, and changes in family relationships are good reasons to review beneficiary choices. Follow the insurer’s procedure rather than relying on…